 Bitcoin
 Ethereum
 Solana
 TRON
 Zcash
 Hyperliquid
 Dogecoin
 Monero
 Chainlink
 Cardano
 Stellar
 Uniswap
 Sui
 Hedera
 Bittensor
 Shiba Inu
 Ripple USD
 Polkadot
 Aster
 World Liberty Financial
 Render
 Artificial Superintelligence Alliance

SUI chopped for weeks. Then it stopped chopping.
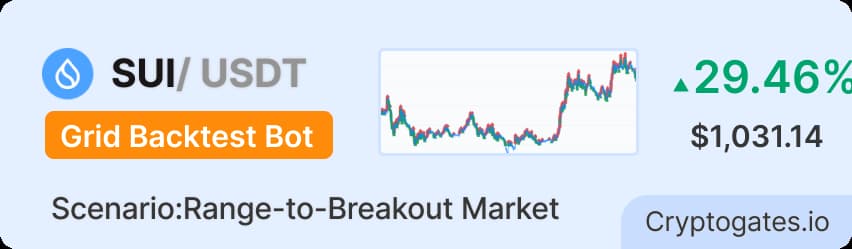
This SUI grid bot backtest opened on March 1, 2025, with SUI at $2.8301. It closed 75 days later, on May 15, at $3.8486 — a 35.99% gain.
That number hides the actual path. SUI spent the first several weeks grinding sideways, dipping as low as $2.0212, before breaking out hard into a sustained rally that carried it toward $4.2989 by early-to-mid May.
Not a clean chop. Not a clean trend either — both, back to back.
The question this SUI/USDT grid trading strategy test was built to answer: does grid density (15 vs. 35 vs. 80 grids) matter more than the market regime itself?
We ran three variants — identical range, identical spacing logic, only the grid count changed — across the full 75-day window using CryptoGates’ Grid Backtest Bot.
Strategy Parameters
How Each Setting Impacted Performance?
Grid bots aren’t complex – but the relationship between parameters and outcomes is.
Here’s what actually drove this result.
Parameter Impact Summary
| Parameter | Impact | The Logic (Why) |
|---|---|---|
| 30-Day Range ($2.02–$4.30) | 🎯 Captured the full move | Wide window held both the dip and the breakout |
| 80 Grids | 🔁 Highest trade count (1,026) | Denser levels, more fills per swing |
| Arithmetic Spacing | ⚖️ Even $0.029 steps | Fixed dollar step regardless of price |
| $43.75 Grid Size | 💰 Full capital deployed | 80 × $43.75 = $3,500 exactly |
| 3% Profit/Grid | 📈 Reliable per-cycle capture | Wide enough margin to clear the 0.1% fee |
| 0.1% Fee Rate | ⚠️ Modest drag at scale | 1,026 trades still cost only ~$49 total |
1,026 trades. $1,068.60 grid profit. $1.01 per completed cycle.
💰 The Bottom Line:
This grid density backtest delivered $1,031.14 net profit on $3,500 deployed — a 29.46% return that lines up exactly with the platform’s own ROI, since the full account (not a recycled sub-balance) was the denominator.
The reported 245.59% annualized figure assumes this 75-day return compounds every cycle for a full year — an aggressive assumption resting on SUI repeating a 36% move on schedule. A straight-line, non-compounding annualization lands closer to ~143%, a fairer number to plan around.
⚡ Density Paid Off, Modestly:
Going from 15 grids to 80 grids added 852 extra trades and only $28.87 more gross profit ($1,039.73 → $1,068.60). Each additional level contributed less than the one before it.
Grid efficiency of 472% shows capital was recycled aggressively — but here, more density bought diminishing returns, not a multiplier.
🛡️ Fee Drag Stayed Contained:
$48.96 in total fees against $1,068.60 gross profit is a 4.58% drag — reasonable for over 1,000 trades at a 0.1% rate.
The $37.46 gap between gross grid profit and net profit comes mostly from a small unrealized markdown on the 99.38 SUI still sitting in inventory at test-end, priced at the $3.8486 close rather than its slightly higher average buy price.
Here comes our A/B/C strategies quick comparison:
| Variant | Range | Grids | Trades | Grid Profit | ROI % |
|---|---|---|---|---|---|
| A | 30-Day | 15 | 174 | $1,039.73 | 28.46% |
| B | 30-Day | 35 | 432 | $1,054.66 | 29.04% |
| CFeatured | 30-Day | 80 | 1,026 | $1,068.60 | 29.46% |
All three variants used the identical 30-day range — grid density was the only lever tested. Going from 15 to 80 grids added 852 trades for just $28.87 in extra gross profit, moving ROI a single percentage point.
Variant B sits almost exactly between A and C on every metric, confirming a smooth, diminishing curve rather than a cliff: more grids kept helping, but each added level bought less than the last. C is featured here as the platform’s highest-ROI configuration — not because density is free.
At 1,026 trades, execution slippage and exchange rate limits become real constraints Variant A never has to face.
What the results are really telling you.
✅ what worked
The 30-day range selector did its job: it stretched from $2.02 to $4.30, wide enough to hold SUI’s entire move without breaking out.
Early trades show the mechanism working exactly as designed — the March 1 log shows SELL fills at $2.85, $2.88, $2.88, $2.91, and $2.91, five completed cycles inside four hours, each clearing 3% net of fees.
That cycling, repeated 1,026 times, built the $1,068.60 gross profit.
⚠️What didn't work
Despite testing three grid densities, every single variant lost to simply holding SUI. Buy & Hold returned 36.24% ($1,268.40) versus the bot’s best result of 29.46% ($1,031.14) — a $237.26 gap.
The reason: SUI’s real edge in this window was a sustained breakout, not chop.
A grid bot sells into every rally leg for a fixed 3%, capping upside that a hold position captured in full.
💡 The key insight
Grid density is a dial, not a fix.
Tripling the grid count from 15 to 80 pushed ROI from 28.46% to 29.46% — real, but marginal, for over 5x the trades and fee exposure. The bigger lesson sits outside the grid settings entirely: no amount of tuning closes a gap that opens because the market trended instead of chopped.
Grid bots are built to harvest a grid bot breakout market poorly — they’re a chop-capture tool.
When SUI shifted from range to breakout mid-test, the strategy kept collecting small, steady wins while the trend ran past it untouched.
🚩 Watch out for - a potential red flag
28.52% max drawdown looks alarming, but it’s in-session unrealized exposure — the low point when SUI dipped toward the $2.02 range floor early in the test, not a locked-in loss.
It recovered because price stayed inside the defined range. The real risk sits at the boundaries: if SUI had broken below $2.02, the bot would have kept buying with no sell trigger, stacking inventory into a falling market with no cap.
Before running this setup: confirm the full $3,500 is liquid and available, and re-run the 30-day range selector fresh — a March–May window is stale the moment new price action happens.
Overall Performance Score, Strengths and Limitations
Solid Execution, Wrong Market for the Edge
29.46% ROI on $3,500 in 75 days is a real, positive result with contained fee drag (4.58%) and a max drawdown that stayed inside a defined range. But the honest comparison matters: in a market that trended instead of chopped, a simple hold beat every grid configuration tested.
🧭 STRENGTHS
- 3% profit/grid comfortably cleared fees across 1,026 trades
- Fee drag stayed low (4.58% of gross profit) even at high trade volume
- Wide 30-day range absorbed the full move without a boundary breakout
- More grid density consistently improved results — no reversal point found
- Max drawdown (28.52%) tracked the actual price dip, not a design flaw
🚫 LIMITATIONS
- Underperformed Buy & Hold by $237.26 (29.46% vs. 36.24%)
- Grid density gains were marginal — 5.9x more trades for +1 ROI point
- 1,026 trades at 0.1% fee assumes ideal, low-slippage execution
- Structurally caps upside during trending/breakout phases
- Range must be recalibrated before every fresh deployment
Quick Takeaways
✔ More grids improved ROI, but with sharply diminishing returns
✔ SUI’s real move was a breakout, not a chop — grids cap trend upside
✔ Buy & Hold beat all three tested variants this cycle
✔ Fee drag stays manageable even at 1,000+ trades, if profit/grid is wide enough
✔ Wide ranges (30-day) protect against boundary breakout in volatile alts
What did spot buy & hold actually return?
If you had simply bought $3,500 of SUI on March 1 at $2.8301 and held through May 15, here’s how it compares:
Running the grid instead of holding cost $237.26 this cycle: $1,268.40 (hold) minus $1,031.14 (bot) net profit. The bot still made money — just less than doing nothing.
In a genuine breakout, a static hold beats even a well-tuned, 80-grid bot.
Before you run this playbook, check these off.
Use this as your go/no-go checklist before deploying this exact parameter set.
🧠 Market Suitability Matrix
| Market Condition | Performance (Rating) | Strategy Notes |
|---|---|---|
| Sideways / Consolidating | ★★★★★ Excellent | First weeks here drove most fills |
| High Volatility | ★★★★☆ Good | Wide range absorbed swings well |
| Mildly Bearish / Slow Bleed | ★★★☆☆ Moderate | Range floor risk if trend continues |
| Mildly Bullish / Slow Climb | ★★★★☆ Good | Grid still cycles, less than hold |
| Strong Bull Run / Breakout | ★★☆☆☆ Risky | Lost to Hold by $237 here |
| Strong Bear / Crash | ★☆☆☆☆ Poor | No sell trigger below range floor |
| Very Low Volatility | ★★☆☆☆ Risky | 1,026 trades needed real movement |
How to tune this playbook for different scenarios.
Disclaimer: All data sourced from CryptoGates Grid Backtest Bot. Results are historical simulations using Binance 1-minute OHLCV data. Past backtest performance does not guarantee future live trading results. DYOR.
Battle-Test Your Strategy
Before the Market Does.
Eliminate guesswork with institutional-grade backtesting for DCA, Grid, and Rebalance bots. Real historical data. Real-world results.